
November 2, 2026
•
5 min read
Hurricane Damage in Mexico: What Your Home Insurance Covers and What to Do First
Hurricane damage to your home in Mexico? Report it within five days, document everything, and see what Mexican home insurance covers and what it leaves out.
Justin Barsketis
Insurance Expert
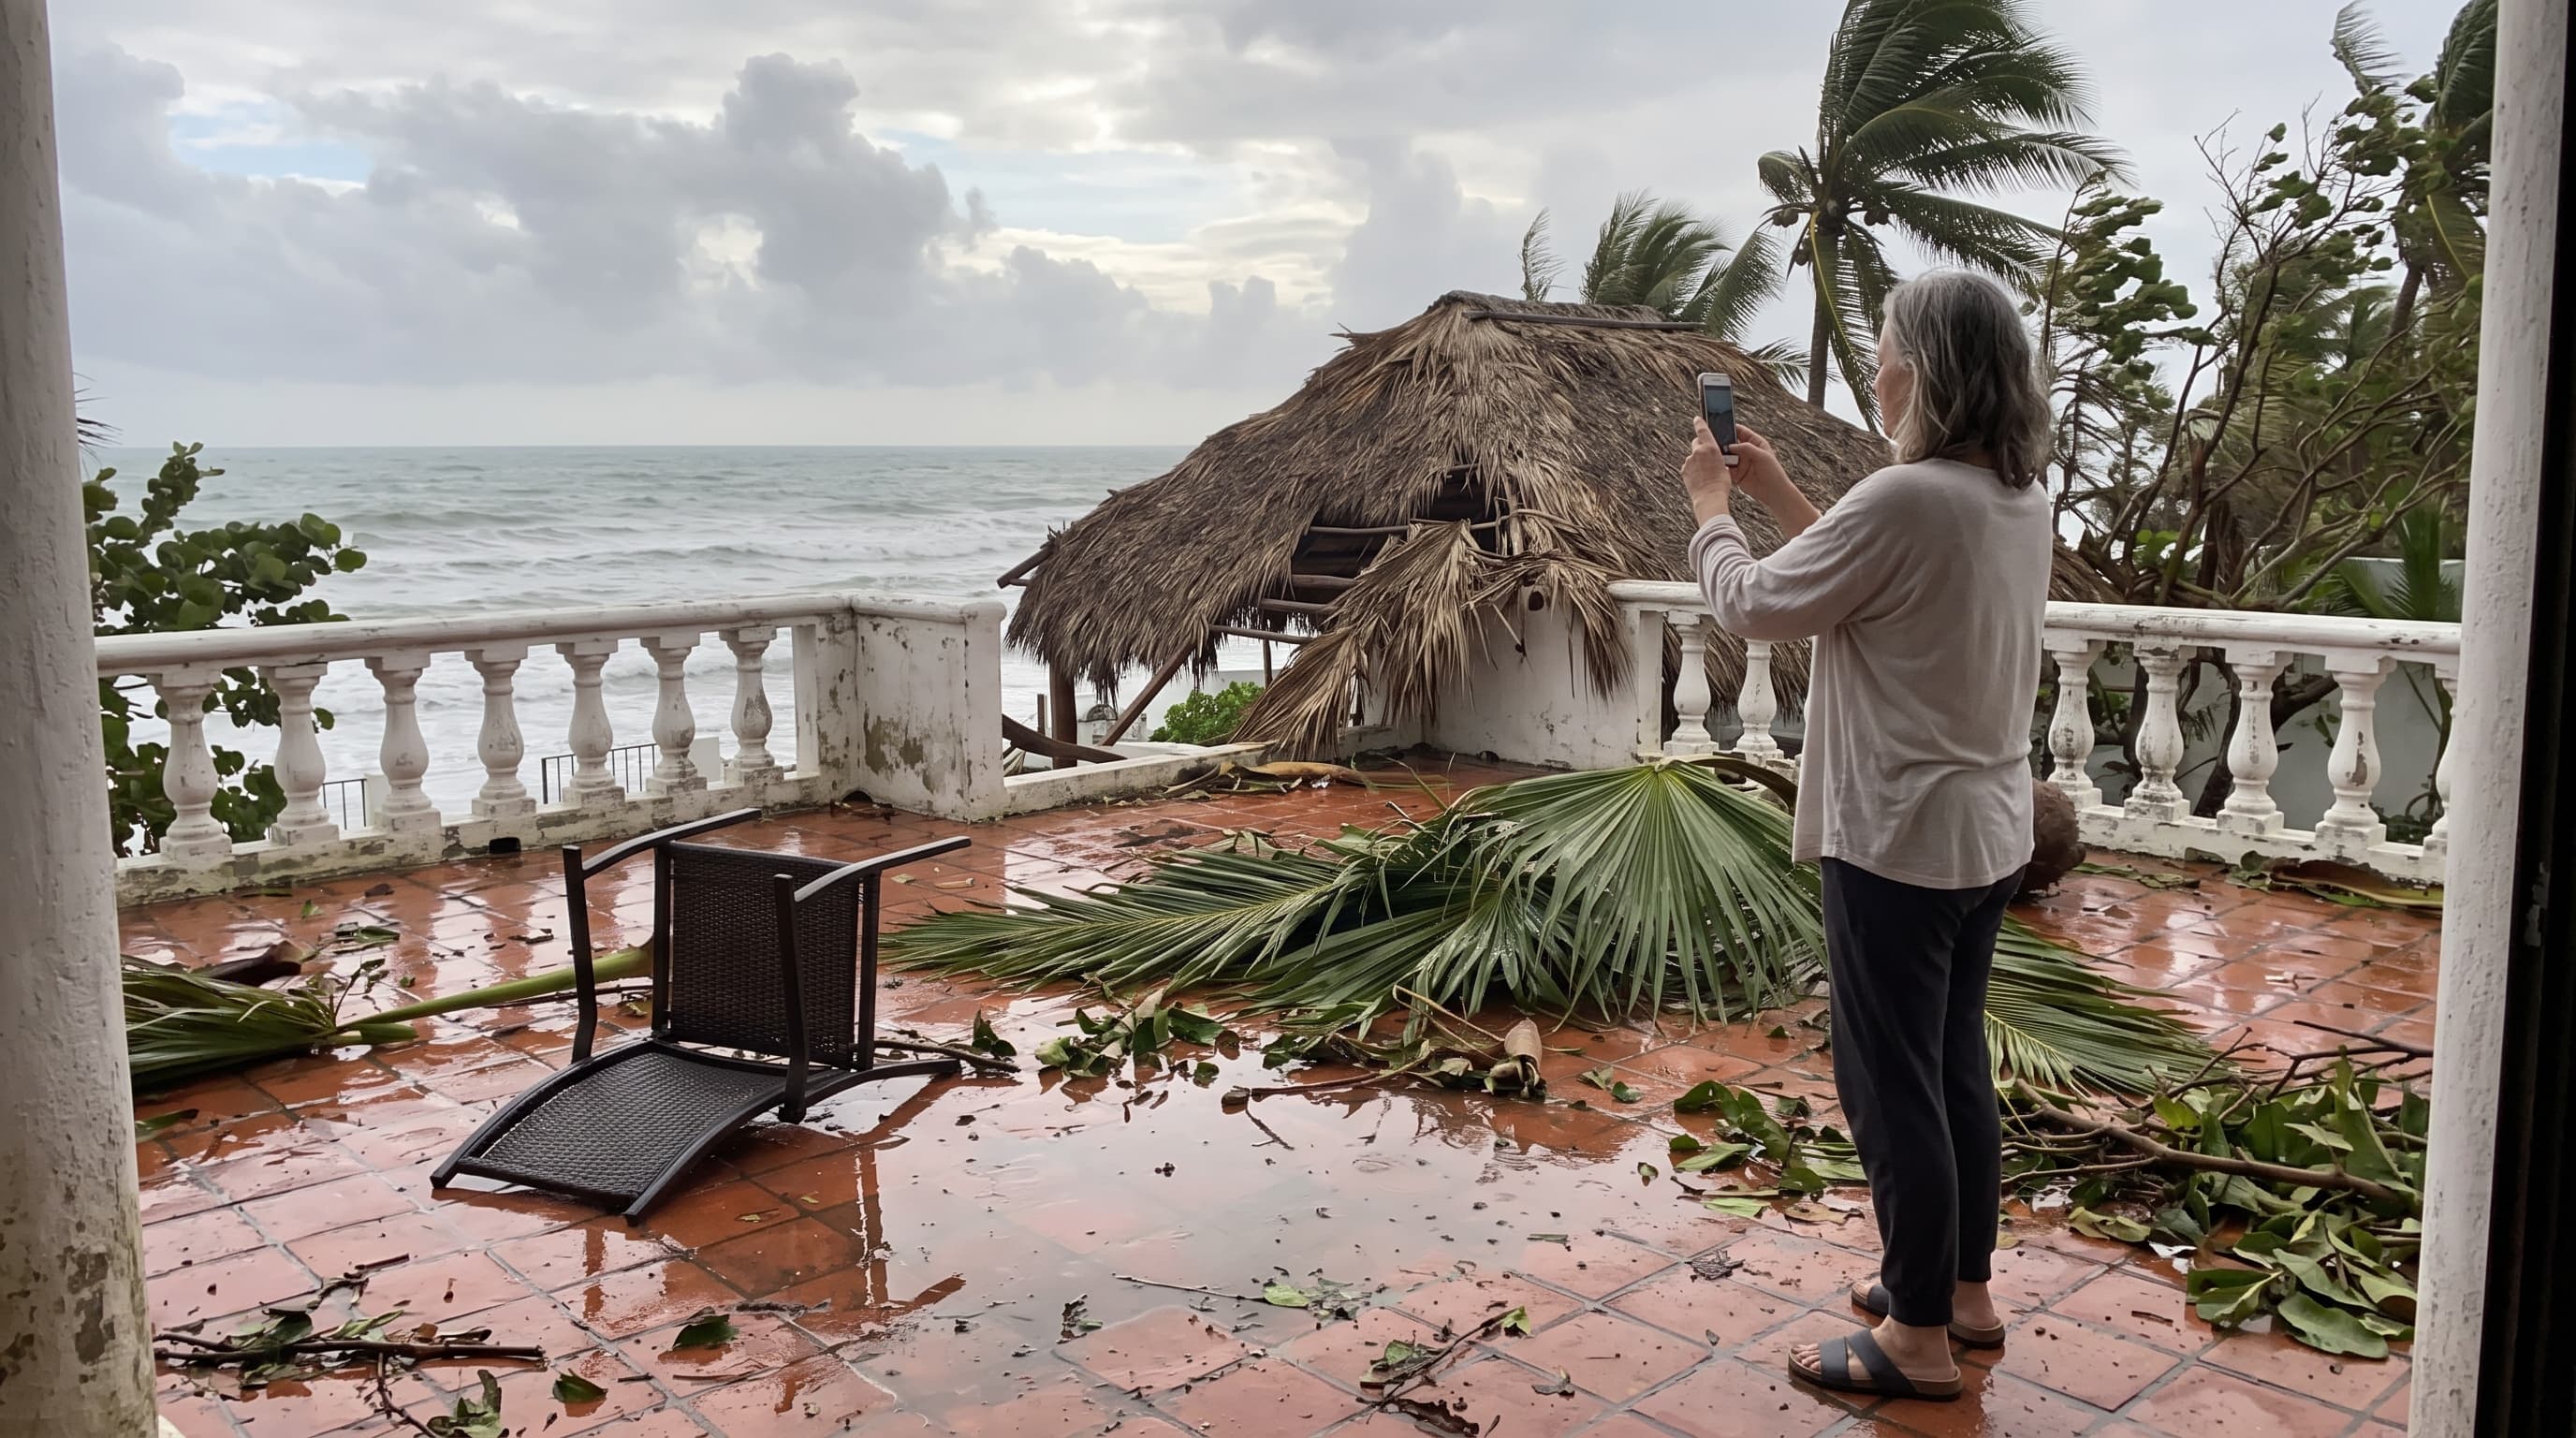
Hurricane damage to your home in Mexico? Report it within five days, document everything, and see what Mexican home insurance covers and what it leaves out.On the night of September 28, Hurricane Polo came ashore in Baja California Sur as a Category 2 storm. By the next morning it had crossed the Gulf of California and hit Guaymas, Sonora, as a Category 1. Baja got off with minor damage. Guaymas and Empalme got flooded streets, downed trees, and power outages.
Hurricane season runs through November 30 on both coasts, and October has a bad record here. Wilma, Patricia, and Otis were all October storms. If your home in Mexico has taken damage, what you do in the first few days affects how much your insurer pays. Here is what to do first, then what a Mexican home policy does and doesn't cover.
Dealing with storm damage and not sure where to start? Book a free 15-minute call with one of our brokers and we'll walk you through it.
Throughout this article you'll see links in blue text. They lead to our other guides and to the sources behind the numbers. This is general information, not a reading of your policy. Your own policy wording decides what gets paid.
What to Do First
Hurricane Damage in Mexico – What to Do First:
– Make Sure the House Is Safe –
Don't go back in until local authorities say you can. Stay away from downed power lines and any standing water near them. If you can reach them safely, shut off the gas and the main breaker. For anything urgent, 911 works throughout Mexico.
– Report the Claim Within Five Days –
This is the deadline people miss. Mexico's insurance contract law gives you a maximum of five days from the moment you learn of the damage to notify your insurer, unless your policy allows more. If you report late, the insurer can reduce what it pays.
Call your broker or the claims line on your policy and get a claim number (número de siniestro). You don't need a full damage list yet. If the storm knocked out phone and internet, report as soon as service is back. If you're out of the country, report based on what your property manager or a neighbor tells you.
– Document Everything Before You Move It –
Take photos and video of every room, inside and out, before you clean up. Get wide shots and close-ups, the waterline on the walls, the roof, and the serial numbers on appliances and electronics.
Keep damaged items until the adjuster has seen them. If something has to go for health reasons, like spoiled food or a soaked mattress, photograph it first.
– Stop the Damage From Getting Worse –
The law requires you to do what you reasonably can to limit the damage, and it requires the insurer to reimburse the reasonable cost of doing it. Tarp the roof, board up broken windows, pump out water, and move what you can to a dry room. Keep every receipt.
– Hold Off on Permanent Repairs –
The same law says you can't change the state of the property without the insurer's consent, except to prevent more damage. Temporary fixes are fine. Permanent ones should wait until the adjuster (ajustador) has inspected or the insurer has approved the work in writing. Ignoring either rule gives the insurer grounds to pay less.
– Get Ready for the Adjuster –
Insurers will ask for:
- A detailed list of what was damaged and what it was worth
- Receipts, invoices, or appraisals that back up the list
- Any other insurance on the same property, such as your HOA's policy
- Photos or video from before the storm, if you have them
Be there for the inspection or send someone you trust. Ask for a copy of the adjuster's report, get at least two contractor quotes to compare against it, and don't sign a final settlement (finiquito) until you agree with the number.
– If You Own a Condo or Hold Title Through a Fideicomiso –
In a condo, tell your HOA administrator right away. The building's master policy usually covers the structure and common areas. Your own policy covers your unit's interior, improvements, and contents, so one storm can mean two claims.
If you hold the property through a fideicomiso, the bank is the legal owner on paper. Confirm with your broker how the trust is named on the policy, because that can affect how the claim gets paid.
Not sure your current policy would hold up in a hurricane? Get a quote in about a minute and compare.
What Your Home Insurance Covers
Hurricane Damage in Mexico – What Your Home Insurance Covers:
Hurricane coverage is not automatic in Mexico. It comes from an add-on called fenómenos hidrometeorológicos (hydrometeorological phenomena). Look at your policy's declarations page (carátula). If that coverage isn't listed, hurricane damage isn't covered.
If it is listed, there's good news for Americans used to buying wind and flood separately. In Mexico, one coverage bundles hurricane, high winds, flooding, storm surge, mudslides, and hail.
– What It Pays For –
- The building: roof, walls, windows, doors, and built-in fixtures
- Your contents, if you insured contents
- Debris removal, temporary living costs, or lost rent, but only if you bought those coverages
– What It Usually Leaves Out –
The standard wording Mexican insurers use excludes more than most owners expect:
- Outdoor property. Palapas, pergolas, pools, fences and gates, patio furniture, outdoor lighting, irrigation, antennas, and water tanks, unless you added them with their own limit.
- Gardens, trees, and beach. Landscaping, docks, and lost beachfront.
- Leaks from poor upkeep. Water that seeps in because of bad waterproofing, missed maintenance, or construction defects. Rain damage inside is covered when the storm itself opened the roof, a wall, a window, or a door.
- Sewer backup. This includes poor drainage on your own lot.
- Slow damage. Mold, rust, and corrosion.
- Outages. Spoiled food and other losses from the power or water being out.
- Looting. Theft during or after the storm is excluded from this coverage.
- Unfinished homes. Buildings under construction or missing parts of the roof or walls.
Policies written for expats can be broader. Some of the ones we place include pools and outdoor kitchens in the building limit, for example. Ask before the storm, not after.
– Deductible and Coinsurance –
A hurricane deductible is a percentage of the insured value, not of the damage. Standard wording sets it at 2% in coastal hurricane zones, and 5% if the home is beachfront, has a glass facade, or has a palapa roof. On the coastal policies we quote, it usually runs 3% to 5%.
Standard wording also adds 10% coinsurance, which is your share of the loss after the deductible. Here's how that works on a home insured for $300,000 with a 2% deductible and $40,000 in damage:
- Deductible: $6,000
- Coinsurance: 10% of the remaining $34,000, or $3,400
- Insurer pays: $30,600
A storm that does $5,000 in damage to that same home pays nothing. Damage that happens within the same 72 hours counts as a single claim. Not every policy applies coinsurance the same way, so check your declarations page.
How Long a Claim Takes
Hurricane Damage in Mexico – How Long a Claim Takes:
By law, the insurer owes payment 30 days after it receives the documents and information that support your claim. The clock starts when your file is complete, so missing paperwork is the usual reason for delay.
After a major storm, expect it to take longer. Seventy-nine days after Hurricane Otis hit Acapulco in 2023, insurers had 17,053 home claims worth an estimated 9.6 billion pesos and had paid out about 1.6 billion. Ask your adjuster for an advance (anticipo) so repairs can start.
If you and the insurer disagree, start with the insurer's own complaints unit. After that, go to CONDUSEF, the federal agency that mediates insurance disputes for free. You have two years from the date of the loss to take legal action.
Contractors are a separate matter. If one takes your deposit and disappears, our guide to consumer rights in Mexico explains where to complain.
If You Don't Have Hurricane Coverage
Hurricane Damage in Mexico – If You Don't Have Hurricane Coverage:
You're not alone. Mexico's insurance association, AMIS, says only 26% of homes in the country carry any insurance. In Polo's path, the figure was 34.9% in Baja California Sur and 39.5% in Sonora.
There's also less of a safety net than many expats assume:
- Federal aid is small. Mexico no longer has its Fonden disaster fund. Aid now comes through a door-to-door census run by the Bienestar ministry. After the October 2025 floods, households got 20,000 pesos up front and 25,000 to 70,000 pesos more depending on the damage. An owner who is out of the country can easily be missed.
- Your policy from home won't help. U.S. and Canadian homeowners policies generally don't cover a house in Mexico.
- You can't buy coverage once a storm is on the way. Insurers commonly stop writing new hurricane coverage when one is forecast, and some programs have a waiting period of 10 to 15 days.
If you're uninsured, the fix is to get covered before the next storm, not during it.
Frequently Asked Questions
Hurricane Damage in Mexico – Frequently Asked Questions:
– Does Mexican home insurance cover hurricanes automatically? –
No. You need hydrometeorological coverage listed on your declarations page. Mexico's financial consumer agency notes that a basic home policy usually doesn't include it.
– Is flood covered separately, like in the U.S.? –
No. Wind, flood, and storm surge are part of the same coverage. One catch: standard wording excludes flooding that is confined to your own property.
– I wasn't in Mexico when the storm hit. What now? –
Report the claim anyway, within five days of learning about the damage. Have your property manager or a neighbor take photos and make temporary repairs, and authorize someone in writing to meet the adjuster.
– Does my HOA's insurance cover my condo? –
Usually only the building's structure and common areas. Ask your administrator for a copy of the master policy and its hurricane deductible, since owners can be billed a special assessment to cover it.
– I rent. Are my belongings covered? –
Not by your landlord's policy, which covers the building. You'd need your own contents policy with hurricane coverage.
– What about my car? –
A Mexican auto policy with physical damage coverage generally covers flood and hurricane damage. Liability-only does not.
– Can I deduct the damage on my U.S. taxes? –
Generally not for a personal-use home. The IRS limits personal casualty losses to federally declared disasters and, starting in 2026, certain state-declared ones. A hurricane in Mexico gets neither. Rental property follows different rules, so ask your tax preparer. Our guide to U.S. and Mexican taxes is a good place to start.
Conclusion
Hurricane Damage in Mexico – Conclusion:
The first week after a hurricane comes down to four things: stay safe, report within five days, document everything, and make only temporary repairs until the adjuster has been through. The rest depends on a policy you bought months earlier. Check now that hydrometeorological coverage is on it and that you know your deductible.
If you'd like a second set of eyes on your policy, or you don't have one yet, get a quote or book a 15-minute call with a broker.
Related Articles:
Justin Barsketis
Insurance Expert & Writer
Justin is an insurance guru that loves digital marketing. As our founder Justin manages our business development programs and MGA network. Please don’t hesitate to contact him if you are not getting the attention you deserve.
